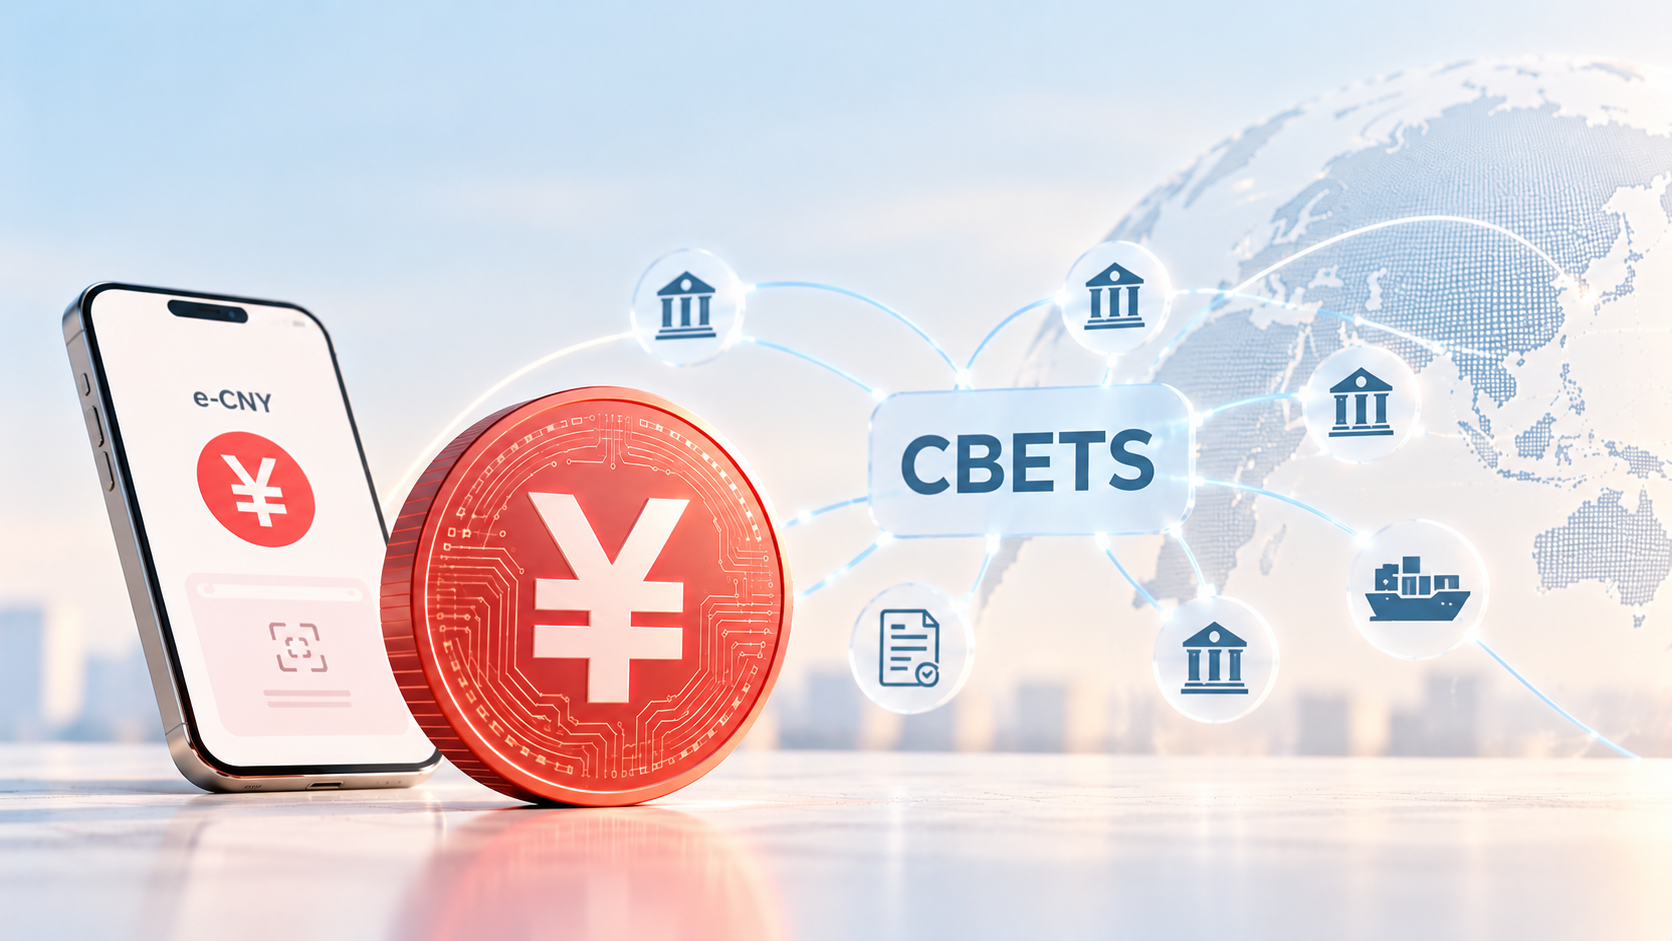
The next phase of China’s digital RMB strategy is characterised by the transition from developing technology behind the currency issuance towards building the infrastructure that can support its international use. The trajectory of the Cross-Border E-CNY Transfer Services (CBETS) (数币达跨境结算综合服务平台) illustrates this shift. When CBETS opened its membership in June 2026, 26 Chinese and overseas financial institutions signed direct participant agreements. By the end of September, a further 39 financial institutions have submitted applications to become its members. The rapid expansion of institutional participation in just three months suggests that CBETS is becoming an important vehicle to leverage China’s early mover advantage for shaping global standards on Central Bank Digital Currencies (CBDCs).
Moreover, its significance extends beyond the number of institutions connected to the platform as it allows Beijing to build the infrastructure that facilitates cross-border usage of digital RMB. Internationalising a digital currency requires banks and other commercial institutions willing to transact in it, mechanisms for accessing and holding liquidity, connections with foreign payment systems and commercial uses that generate sustained demand. While China’s Cross-border Interbank Payment System (CIPS) enables clearing and settlement system for conventional interbank payments, CBETS complements it as the mechanism through which China is attempting to build these conditions around digital RMB.
Strategic Logic of CBETS
CBETS is the product of a broader institutional effort to extend the digital RMB beyond China’s domestic payments system. Launched alongside the Digital RMB International Operations Center in September 2025, CBETS consolidated and upgraded several existing cross-border digital payment and blockchain functions. Its development was driven partly by the frictions inherent in conventional cross-border payments, where transactions can pass through multiple intermediary banks and require repeated message verification and compliance checks, adding both time and cost to settlement. CBETS seeks to address these constraints by establishing more direct connections between Chinese and overseas financial institutions and, where appropriate, between payment systems, while enabling round-the-clock digital RMB services.
Foreign financial institutions are also central to this model as the branch of Standard Chartered in China was among the first institutions to sign a direct participation agreement, alongside overseas branches of Chinese banks based in Asian and South American countries. The growing participation of such institutions also gives China a mechanism for testing whether digital RMB settlement can generate genuine commercial demand rather than relying solely on state-led adoption.
Further, CBETS complements rather than replaces China’s existing financial infrastructure. CIPS continues to support conventional RMB settlement, while the existing mBridge Project provides a multilateral framework for interoperability between different CBDCs. China’s decision to develop CBETS alongside mBridge reflects the need for a more commercially oriented infrastructure. While Yuan accounts for nearly 95 percent of transactions volume between central banks under mBridge, CBETS gives overseas commercial banks direct exclusive access to China’s e-CNY infrastructure. This allows Beijing to exercise greater control over the access, settlement and commercial applications of the digital RMB while expanding its use through foreign financial institutions. Thus, CBETS fills a gap that mBridge alone cannot address by turning digital RMB into a platform that foreign banks can access and build commercial services around.
Its strategic importance also lies in extending China's influence from digital currency issuance to the infrastructure governing how cross-border digital transactions are conducted. Its development is aimed at gradually extending this infrastructure for trade settlement and overseas financing, embedding digital RMB more deeply in China-centred commercial flows. It thus forms part of the institutional infrastructure needed to give the digital RMB sustained economic utility beyond China.
From Access to Commercial Adoption
The key challenge for Beijing is to turn cross-border access to the digital RMB into sustained commercial use. CBETS is beginning to address this by expanding beyond payment settlement into the wider financial activities that support cross-border commerce.
Its expansion in Asia provides an early indication of the direction. For instance, in September, CBETS was connected to Laos’ national payment network, LAPNet, enabling interoperability between digital RMB and local QR payments. Earlier, Bank of China also completed its first batch of cross-border retail digital RMB transactions through CBETS in Singapore, demonstrating how the platform can support both wholesale and retail transactions. A more consequential step came with the launch of CBETS LIFT in September, which expands digital RMB in cross-border trade settlements and investment financing. It strengthens its role in cross-border commerce by facilitating these transactions within the same ecosystem, increasing attractiveness of digital RMB for overseas businesses.
This makes the digital RMB part of the wider commercial transactions that aims to generate sustained demand for a currency. Embedding the digital RMB within trade and investment transactions can create incentives for foreign institutions. By integrating payment, trade documentation and financing, CBETS can further strengthen the practical utility of RMB beyond individual transactions. Thus, it seeks to build the commercial conditions that could give the digital RMB a more durable role in China’s external economic relations and the wider global economy.
CBETS and the Future of RMB Internationalisation
CBETS is unlikely to immediately challenge the dollar-based international monetary system. Its more durable role lies in reducing the practical barriers to using RMB in economic relationships involving China. CBETS infrastructure alone cannot facilitate the RMB internationalisation as it continues to face structural constraints, including restrictions on capital mobility, the relative depth and openness of its financial markets and the global availability of RMB-denominated assets. What CBETS can change is the cost and convenience of RMB transactions. If Chinese and foreign institutions can connect directly through digital RMB infrastructure, access liquidity and settle trade, the incentives for using RMB can gradually improve. Repeated use can, in turn, generate greater familiarity with the currency and expand the range of transactions in which RMB settlement becomes commercially attractive.
However, while CBETS lowers the operational costs of using digital RMB, it does not eliminate a more fundamental constraint: foreign firms may be willing to transact in RMB but remain reluctant to hold substantial RMB balances due to China's capital controls and the limited availability of attractive RMB-denominated investment assets. Similarly, many countries still do not have operational CBDCs or the infrastructure needed to connect their domestic payment systems with a foreign digital currency. This could potentially limit the willingness of overseas banks and businesses to transact in digital RMB.
The rapid expansion of CBETS participation suggests growing institutional interest, but its long-term effectiveness will ultimately depend on actual commercial adoption. The real measure of its success will be whether businesses and financial institutions find sustained value in using digital RMB for trade, financing and other cross-border transactions. CBETS reflects a broader evolution in China's digital RMB strategy – from experimenting with the technology of a central bank digital currency to cultivating the institutional networks necessary for its international adoption. If CBETS succeeds in attracting more users in the coming years, it could gradually transform digital RMB from a domestic payment innovation into a crucial instrument of China’s international economic statecraft.
Author
Omkar Bhole
Omkar Bhole is a Senior Research Associate at the Organisation for Research on China and Asia (ORCA). He has studied Chinese language up to HSK4 and completed Masters in China Studies from Somaiya University, Mumbai. He has previously worked as a Chinese language instructor in Mumbai and Pune. His research interests are India’s neighbourhood policy, China’s foreign policy in South Asia, economic transformation and current dynamics of Chinese economy and its domestic politics. He was previously associated with the Institute of Chinese Studies (ICS) and What China Reads. He has also presented papers at several conferences on China. Omkar is currently working on understanding China’s Digital Yuan initiative and its implications for the South Asian region including India. He can be reached at [email protected] and @bhole_omkar on Twitter.